On This Page8 sections
Key Takeaways
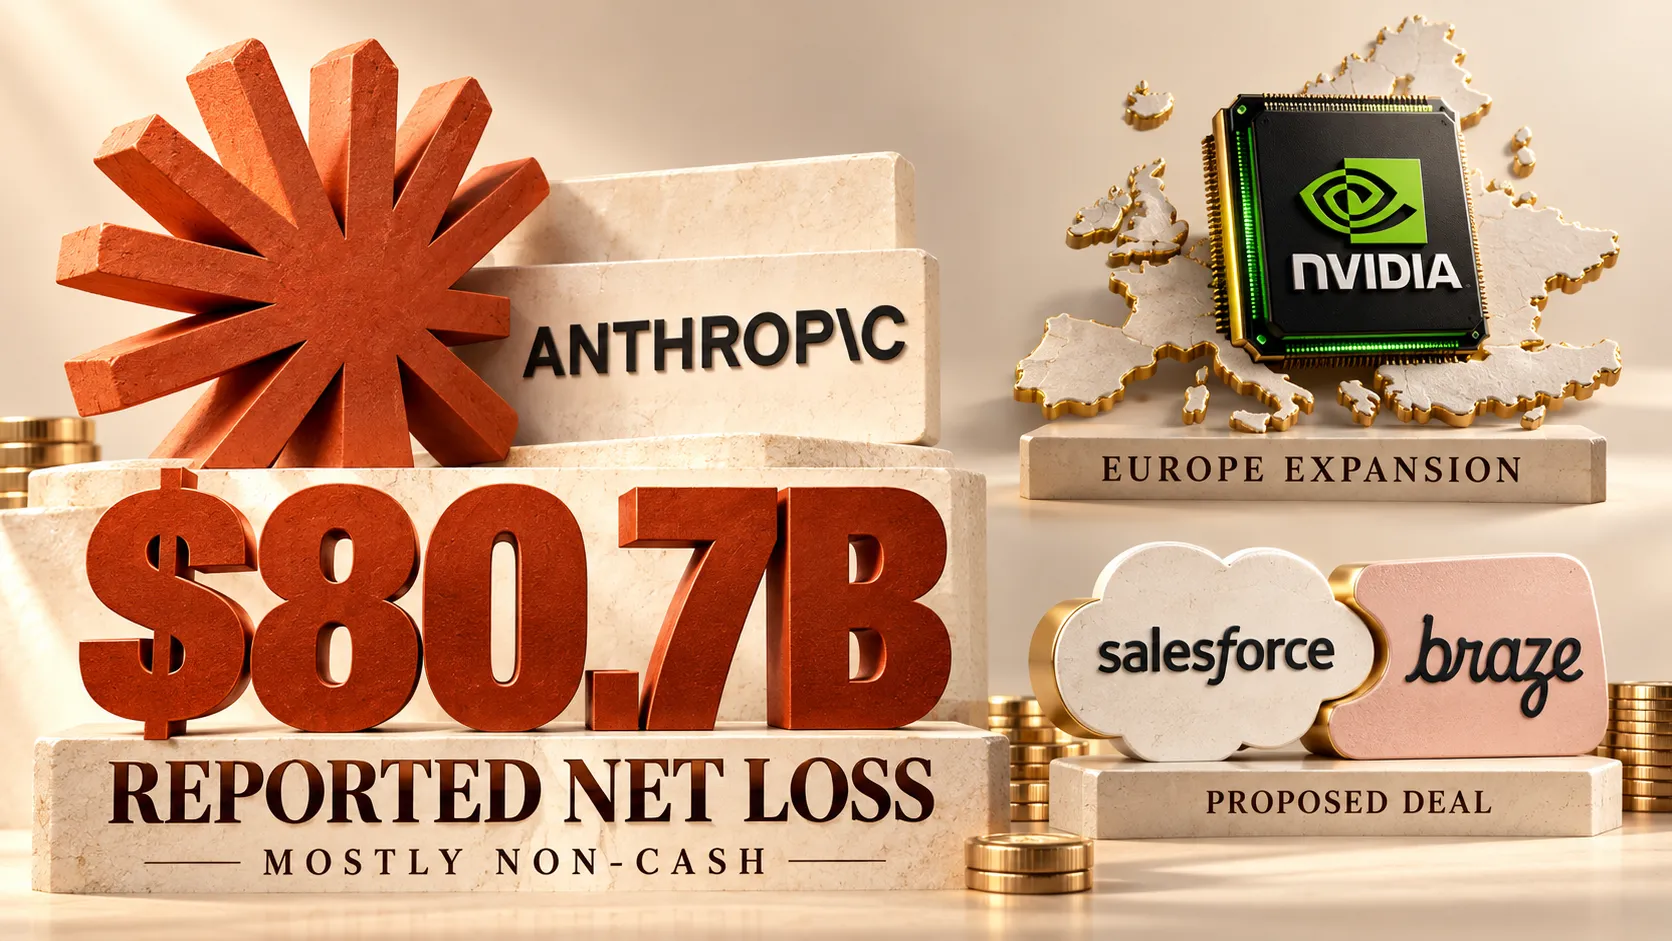
- Anthropic’s reported $80.7 billion net loss does not equal cash burned. A large financing-related accounting charge dominates the figure.
- NVIDIA describes a nearly $10 billion European ecosystem commitment. Its announcements include planned startup investments, research support and infrastructure partnerships with different delivery timelines.
- Salesforce has agreed to acquire Braze at approximately $5.66 billion in enterprise value. Shareholders would receive $47.50 per share in cash, subject to completion of the transaction.
- The shared economic question is whether AI investment generates sustainable customer spending. Model providers need affordable capacity, infrastructure suppliers need paying users, and enterprise software vendors need measurable business outcomes.
Updated October 22, 2026. Dollar amounts are in U.S. dollars.
These three developments describe different parts of the AI economy: financing frontier models, expanding computing capacity and turning customer data into commercial activity.
They also involve fundamentally different financial measurements. A net loss is an accounting result over a period. An investment commitment can extend across years. An acquisition’s enterprise value measures the business being purchased. Adding these headline amounts together would produce a misleading picture of current AI spending.
Anthropic’s $80.7 Billion Net Loss Explained
Anthropic announced its confidential submission of a draft S-1 on June 1, 2026. That announcement established a potential route to an IPO; it did not set an offering price or guarantee a listing.
On October 20, Reuters reported that a draft prospectus showed a $80.7 billion first-half net loss, including a $72 billion charge associated with an increase in the estimated value of bonds convertible into shares.
Separately reported operating figures illustrate the company’s expansion:
| Metric | First half of 2026 | First half of 2025 |
|---|---|---|
| Revenue | $16.3 billion | $1.1 billion |
| Computing and infrastructure spending | Nearly $9 billion | Approximately $2.3 billion |
These figures were reported from the draft IPO disclosures. Revenue increased approximately 14.8 times, while computing and infrastructure spending rose approximately 3.9 times.
The different growth rates are interesting, but they do not establish a gross margin. Infrastructure spending can include items with different accounting treatments and payment schedules. It cannot automatically be substituted for cost of revenue.
Why a Financing Charge Can Produce Such a Large Loss
The reported charge reflects a change in the value of financing instruments. Its scale does not mean Anthropic transferred the same amount of cash to suppliers during the reporting period.
Using the reported figures, the charge represents approximately 89.2% of the headline loss. Subtracting it leaves $8.7 billion, but that arithmetic remainder is not a disclosed operating loss, cash-burn figure or reconciled adjusted earnings measure.
The SEC’s financial statement guide explains the broader distinction: operating cash flow reconciles net income with noncash items and changes in operating assets and liabilities. Assessing liquidity also requires the balance sheet and investing and financing cash flows.
Two questions therefore need separate answers:
- What drove the reported loss? This requires the income statement and financing-instrument disclosures.
- How much funding does the business need? This requires cash balances, cash flows, payment obligations and available financing.
A noncash charge can explain an alarming headline without resolving the underlying business model. Equally, rapid revenue growth does not prove that each additional dollar of revenue generates an attractive return after inference, research and customer acquisition costs.
Anthropic’s Longer-Term Challenge: Computing Commitments
The Wall Street Journal’s investigation reported approximately $450 billion in cloud agreements over seven to ten years. Including a Google-chip leasing arrangement involving Broadcom, future infrastructure obligations exceeded $600 billion; additional negotiations could lift the potential total toward $750 billion. These are overlapping totals, not separate amounts to add together.
The commercial tradeoff is substantial. Securing capacity early can protect a model provider against supply shortages. It can also leave the company with commitments that are difficult to adjust if demand, pricing or hardware economics change.
A useful assessment should examine four issues:
- Payment timing. A multiyear commitment matters differently depending on deposits, annual minimums and when capacity becomes available.
- Demand durability. Recurring production workloads provide stronger support for long contracts than temporary experimentation.
- Price and efficiency. Lower inference costs help only if competitive price reductions and rising usage do not absorb the savings.
- Flexibility. Contract provisions governing capacity changes, delivery delays and technology upgrades can materially affect the economics.
The central question is whether future customer receipts can support the timing and scale of infrastructure payments while funding continued model development.
NVIDIA’s European Investment Push: The 13 Announced Targets
NVIDIA’s October announcements identify 13 planned startup investments across France, the United Kingdom and Germany. The company lists them in its French announcement, UK announcement and German announcement.
The table groups companies by the country announcement in which they appear. Planned investment status should not be confused with confirmation that every transaction has closed.
| Country announcement | Company | Main business focus |
|---|---|---|
| France | Doctolib | Healthcare technology and clinical AI agents |
| France | Entalpic | Materials discovery and semiconductor-related materials engineering |
| France | Genesis AI | General-purpose robotics and physical AI |
| France | Pigment | Enterprise planning, forecasting and scenario analysis |
| United Kingdom | Boltz | Biomolecular models and drug discovery |
| United Kingdom | Foresight | Infrastructure project forecasting and delivery risk |
| United Kingdom | Hiverge | Automated algorithm discovery and optimization |
| United Kingdom | Prima Mente | Biological foundation models and disease research |
| United Kingdom | Riverlane | Quantum error-correction hardware and software |
| Germany | Agile Robots | Industrial robotics and humanoid systems |
| Germany | Avelios Medical | Hospital information systems and clinical workflows |
| Germany | Mirelo | AI-generated audio for video |
| Germany | Reflex Aerospace | Satellite design and manufacturing |
The business descriptions come from NVIDIA’s country announcements.
The breadth of the portfolio is strategically significant. The announced targets extend beyond general-purpose language models into industries with distinct workloads, customers and procurement cycles.
The commercial inference is that NVIDIA is helping develop more places where accelerated computing can become useful. A successful robotics, scientific discovery or industrial software company can create demand across training, simulation and deployment.
That interpretation does not establish any individual startup’s purchasing obligations, nor does it mean every investment will translate into profitable GPU demand.
Beyond Startup Stakes: Research Support and Faster Deployment
NVIDIA’s European activity also includes arrangements that should be evaluated separately from equity investments.
UK research support: NVIDIA announced a five-year compute donation valued at $250 million, equivalent to $50 million in annual compute access. It is intended to support agentic safety and security research through UK-based cloud partners. This is a computing-resource commitment, rather than an equivalent unrestricted cash grant.
German industrial cooperation: On October 19, NVIDIA and German government representatives signed a declaration of intent concerning industrial and physical AI. A declaration establishes a cooperation framework; it does not itself establish commercial deployment results.
Modular infrastructure: At GTC Berlin on October 21, NVIDIA introduced DSX POD, a reference design for factory-integrated, containerized AI infrastructure. NVIDIA says deployment at a prepared site can take as little as 14 days, with partner offerings expected in early 2027.
The prepared-site condition matters. Power, cooling, networking and supporting infrastructure must already be available. The announcement does not imply that a developer can acquire land, obtain approvals, secure electricity and launch a complete data center in two weeks.
The economic rationale is nevertheless clear: earlier production can reduce the time between capital spending and customer revenue. Whether that improves returns depends on utilization, operating costs and paying demand once the installation is running.
Does NVIDIA’s Strategy Create Circular Financing Risk?
A supplier investing in potential customers creates an economic relationship worth examining. If an investee subsequently buys that supplier’s products or related cloud capacity, financing and sales can reinforce one another.
That structure alone does not demonstrate artificial demand or improper accounting. A startup can receive strategic investment and still build a valuable business with independent paying customers.
The useful questions concern the underlying transactions:
- Are procurement commitments attached to the investment?
- How much customer spending depends on fresh fundraising or subsidized credits?
- Does the investee earn recurring revenue from unrelated customers?
- Can installed capacity achieve acceptable utilization after introductory support ends?
- Are financing, revenue and cash collection clearly distinguished?
These are analytical questions, not allegations about the 13 announced investments. NVIDIA’s country announcements do not provide enough transaction-level detail to answer them for every company.
Salesforce’s Braze Acquisition: Price, Terms and Status
Salesforce announced its agreement to acquire Braze on October 20, 2026.
| Transaction item | Announced terms |
|---|---|
| Enterprise value | Approximately $5.66 billion |
| Consideration | $47.50 cash per Class A share |
| Agreement date | October 19, 2026 |
| Expected completion | Salesforce fiscal year 2028 |
| Closing requirements | Shareholder approval, regulatory approvals and other conditions |
The announcement and Braze’s SEC filing describe an agreed transaction awaiting completion. Salesforce’s fiscal-year label should also not be read as a calendar-year closing date.
The filing specifies a $300 million Salesforce termination fee and a $191.39 million Braze termination fee under defined circumstances. These are conditional contractual provisions, not automatic payments whenever either party wants to withdraw.
Enterprise value also differs from the aggregate cash paid for outstanding shares. It reflects a business valuation framework that accounts for financing and balance-sheet items; it should not be casually relabeled as equity value.
What Salesforce Wants From Braze
Braze processes customer events and coordinates personalized interactions across applications, websites and messaging channels. Salesforce expects those capabilities to strengthen Marketing Cloud and complement its customer-data and AI architecture after closing.
The strategic appeal becomes clearer through an illustrative subscription-product workflow:
- A customer starts a trial and completes an initial task.
- Subsequent behavior indicates whether the customer is progressing or becoming inactive.
- A decision process selects an appropriate next action, subject to communication preferences and campaign rules.
- The platform delivers the interaction through an eligible channel.
- Purchase, retention and unsubscribe outcomes feed back into evaluation.
This is an illustrative workflow, not a newly announced Salesforce–Braze integration.
The commercial value lies in connecting customer understanding with timely execution. Generating persuasive copy is only one component. The system must also identify the correct person, interpret current behavior, choose an appropriate action and determine whether the interaction improved an outcome.
For implementation teams, difficult edge cases include duplicate events, delayed purchases, conflicting campaigns and users who change consent preferences between audience selection and message delivery. These operational details can determine whether personalization improves the customer experience or produces unwanted messages.
Braze’s Financials Put the Deal in Context
Braze’s fiscal second-quarter 2027 results, covering the quarter ended July 31, 2026, provide a basis for evaluating the target business.
| Metric | Reported result |
|---|---|
| Quarterly revenue | $227.2 million |
| Year-over-year revenue growth | 26.2% |
| Dollar-based net retention | 110% |
| GAAP operating loss | $18.1 million |
| Non-GAAP operating income | $22.0 million |
| Free cash flow | $21.7 million |
| FY2027 revenue guidance | $910 million–$913 million |
Braze’s FY2027 ends January 31, 2027. The company reports GAAP and non-GAAP measures separately and provides reconciliations.
Dividing the announced enterprise value by the $911.5 million midpoint of that revenue guidance produces approximately 6.2 times expected annual revenue. This is a calculated EV-to-revenue multiple, not an earnings multiple or a forecast of acquisition returns.
The operating loss and positive free cash flow can coexist because accounting expense recognition and cash timing differ. Likewise, non-GAAP operating income excludes specified expenses; it should not be presented as GAAP profitability.
For Salesforce, a successful acquisition would need to produce benefits through some combination of customer growth, stronger retention, cross-selling and operating efficiency. Those benefits must be assessed alongside integration costs and the purchase price.
What These Deals Mean for AI Builders and Software Buyers
The following implications are analytical conclusions drawn from the three developments, rather than announced commitments by the companies.
| Business decision | Practical implication | Useful evidence |
|---|---|---|
| Choosing an AI model provider | Evaluate economic resilience alongside model quality | Reliability, pricing changes, usage economics and contractual terms |
| Buying computing capacity | Match commitments to realistic demand | Utilization, delivery dates, minimum payments and expansion options |
| Adopting AI marketing | Measure incremental business impact | Controlled comparisons of conversion, retention and contribution margin |
| Selecting enterprise software | Preserve operational flexibility through an acquisition | Data exports, integration support, renewal terms and product-roadmap clarity |
For smaller AI products, cost per successful customer outcome can be more informative than cost per token alone. A cheaper request may be less economical if it requires more retries, human corrections or abandoned workflows.
A practical internal calculation is customer revenue minus directly attributable inference, storage, payment and support costs. Teams should label this contribution measure clearly because it does not include every corporate expense.
Marketing measurement requires similar discipline. A customer who receives a message and later purchases may have purchased anyway. A holdout group helps estimate the incremental benefit, while monitoring unsubscribes and complaints reveals whether short-term conversion comes at a longer-term cost.
These are narrower, measurable problems that small teams can address without attempting to reproduce a frontier-model laboratory, a chip ecosystem or an enterprise software suite.
What to Watch Next
For Anthropic: Watch for fuller financial disclosures, cash-flow information, the treatment of financing instruments and the timing of infrastructure obligations. Any adjusted profitability claim should be evaluated with its definition and reconciliation.
For NVIDIA: Track which planned investments close, which infrastructure projects reach production and whether deployed capacity attracts sustained paying workloads. Announced capacity and utilized capacity are different milestones.
For Salesforce and Braze: Follow shareholder and regulatory decisions, followed by concrete integration plans if the transaction closes. Customers should evaluate actual changes to pricing, support and interoperability as they are announced.
Across all three stories, the strongest evidence will connect a financial commitment to a delivered service and a measurable customer outcome.
Conclusion
Anthropic’s loss disclosures, NVIDIA’s European expansion and Salesforce’s proposed Braze acquisition show how much of the AI industry’s competition now depends on financing, infrastructure and commercial execution.
The most useful analysis separates accounting results from cash requirements, planned commitments from completed deployments, and strategic intentions from demonstrated returns.
Before making an AI spending or vendor decision, review the underlying disclosures and define the outcome the investment must deliver. Track the cost of producing that outcome, the durability of customer demand and the flexibility to change course when the economics change.
Continue Reading
More articles connected to the same themes, protocols, and tools.
Referenced Tools
Browse entries that are adjacent to the topics covered in this article.